

Lately, it feels like I can’t catch a break, no matter what I do.
I bought a condo in the last week of June, only to deal with a roof leak in the first week of July. I graduated in September after four years of learning about money, then found myself confronting debt and being cash-poor as the bills kept piling up. I’m getting cooked trading options. And my ongoing legal battle hit another setback, adding pressure to an already difficult financial situation.
And now this.
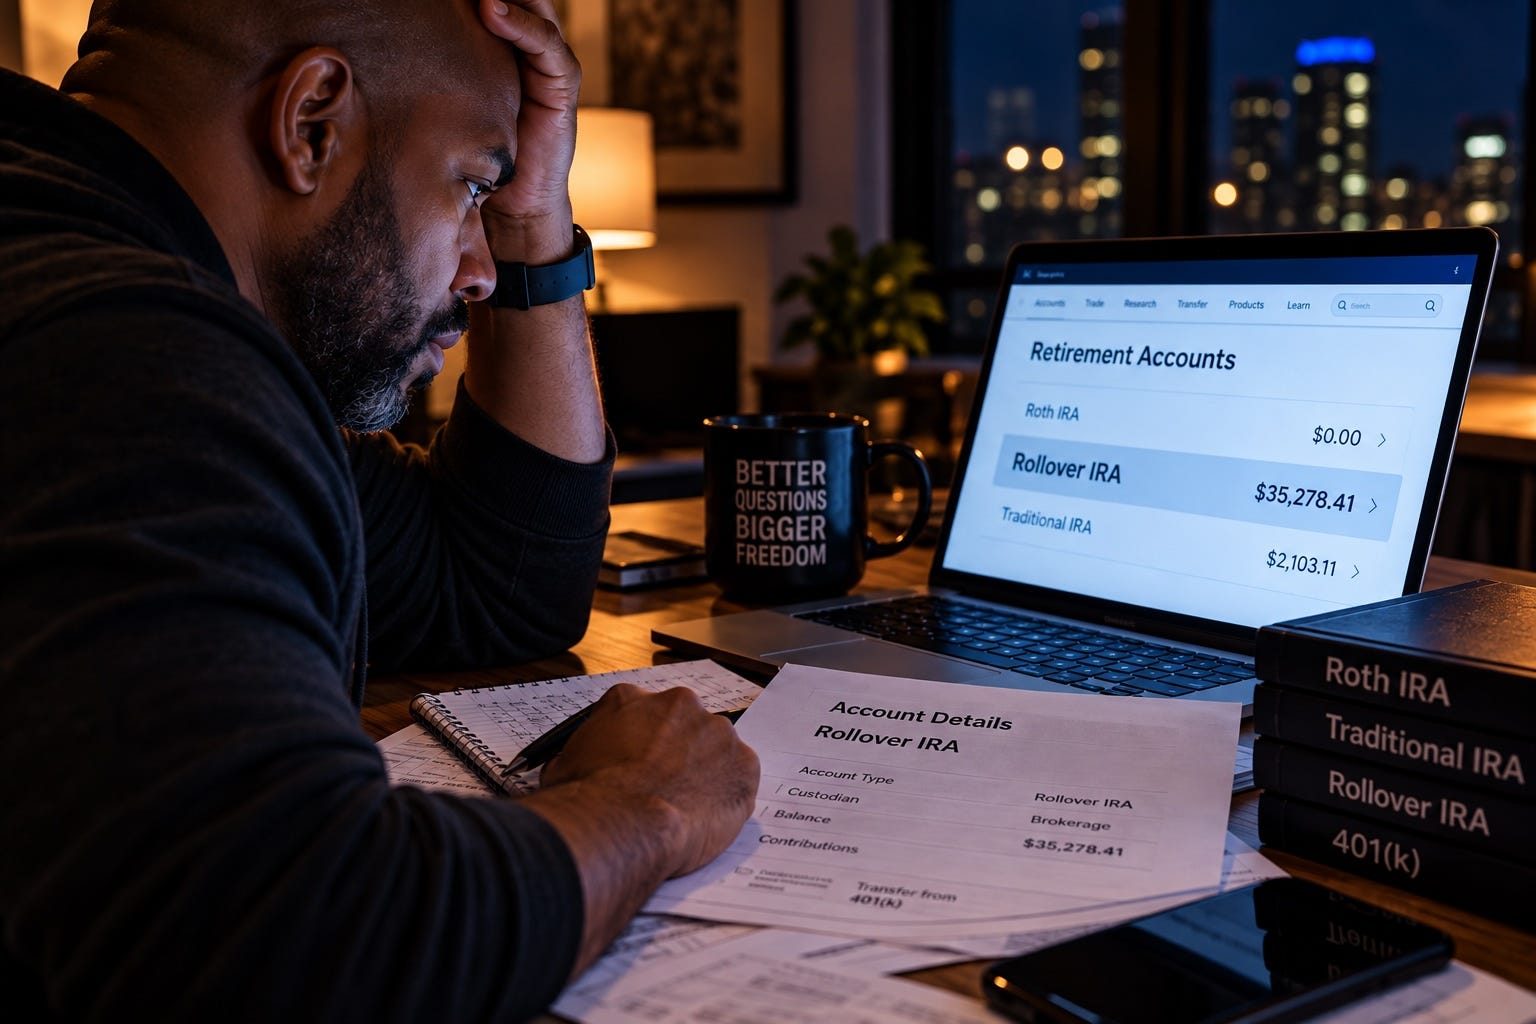
I learned that the retirement account I’ve been calling my Roth IRA for nearly four years is not a Roth at all. It’s a Rollover IRA.
The discovery came at about 1 a.m. on Sept. 30, when I hit a snag trying to transfer my investments from Charles Schwab to Vanguard.
Schwab was charging me $75 every time I purchased VTSAX, Vanguard’s Total Stock Market Index Fund. I wanted to stop paying the fee, which would save me $900 annually, so I decided to transfer my investments in kind, without selling them.
But I couldn’t get the money designated for the Roth IRA I’d opened at Vanguard. Something wasn’t adding up, so I called representatives at both brokerages the next day.
That’s when the representatives told me what had been staring me in the face all along: My account had been labeled “Rollover IRA” the entire time. I simply never stopped to check what I owned.
The information was right in front of me. I even overlooked the language on my tax returns.
I knew what a Roth IRA was. I understood its benefits, the rules and the long-term strategy. I thought I was doing everything right to build my Roth retirement savings.
I was wrong.
The clues were there. I just missed them.
I’d been writing about maxing out my Roth IRA for years without realizing I was publicly describing the account incorrectly.
In September 2023, I published a column about my retirement mistakes and laid out my investment plan for what I believed was my Roth IRA. In April 2024, I wrote about tax efficiency and the importance of prioritizing tax-advantaged accounts. I referred to it as my Roth then, too.
The subhead on that column even asked: “Are your investments structured properly?”
I wasn’t just mistaken in private. I’d been sharing my understanding of my financial journey publicly without catching a glaring mistake in my own account.
That’s on me.
It’s frustrating. Just when I feel like I’m turning a corner, something else pops up. Clearly, I’m not done yet.
The distinction between these accounts matters. A Rollover IRA generally holds money transferred from an employer-sponsored retirement plan, such as a 401(k). A Roth IRA follows different tax rules, including how contributions, conversions and qualified withdrawals are treated.
I’d mistakenly assumed that because I wasn’t paying taxes on investment gains or reporting individual trades on my tax returns, the account had to be a Roth. But traditional IRAs generally also allow investments to grow without annual taxes on trades inside the account.
My original retirement money came from an employer-sponsored 401(k), and the contributions I made afterward are another piece of the puzzle.
I still intend to move my funds toward a Roth IRA, but I need to understand the tax implications before making that decision. Converting pretax money to a Roth IRA can create a taxable event, and moving everything at once could result in a significant tax bill. I’m weighing my options, including whether converting the money over several years makes more sense than doing it all at once.
There’s also the five-year rule for qualified Roth IRA withdrawals. Because I’ve never contributed to a Roth IRA, I haven’t started the five-year clock. I’m still a long way from age 59 1/2, so it’s frustrating, but hardly the end of the world.
It’s a harsh reminder that knowing the rules doesn’t guarantee you’ve applied them correctly.
My head is spinning trying to untangle all of this. And I can see why so many people never bother playing the money game. The rules are complicated, the fine print is endless, and the whole maze is enough to induce a migraine.
But I’m determined to keep playing.
The more I learn, the more the rules start to make sense.
This is an uncomfortable realization, but a valuable moment of clarity. I can’t undo the mistake. I can own it, learn from it and make better-informed decisions going forward.
And I’ve got a lot more homework to do.


Disclaimer: The information contained on Money Talks is not intended as, and should not be understood or construed as, financial advice. I am not an attorney, accountant or financial advisor. These are my personal experiences, and neither this website, newsletter nor podcast is a substitute for advice from a qualified professional.
It's great you're sharing these mistakes so others can see potential pitfalls for themselves. I realized last year that I had an old rollover account that I thought I'd converted to Roth but I had only converted part of it so not to take the tax hit all in the same year. I had just never gone back to convert the rest. I'm not going to convert now in my highest earning years but instead wait to convert when I retire early and have a few key years of lower income before converting will affect my Medicare premiums. It is indeed a tangled web. I'm glad you caught it now and can correct course. Time to start building the tax free portion of your retirement.