

I thought I was beyond this stage of my financial journey.
I thought I’d made enough progress to turn a corner.
I thought I’d learned enough and made enough changes to put some of these struggles behind me.
I was wrong.
And it’s heartbreaking having to admit that to myself.
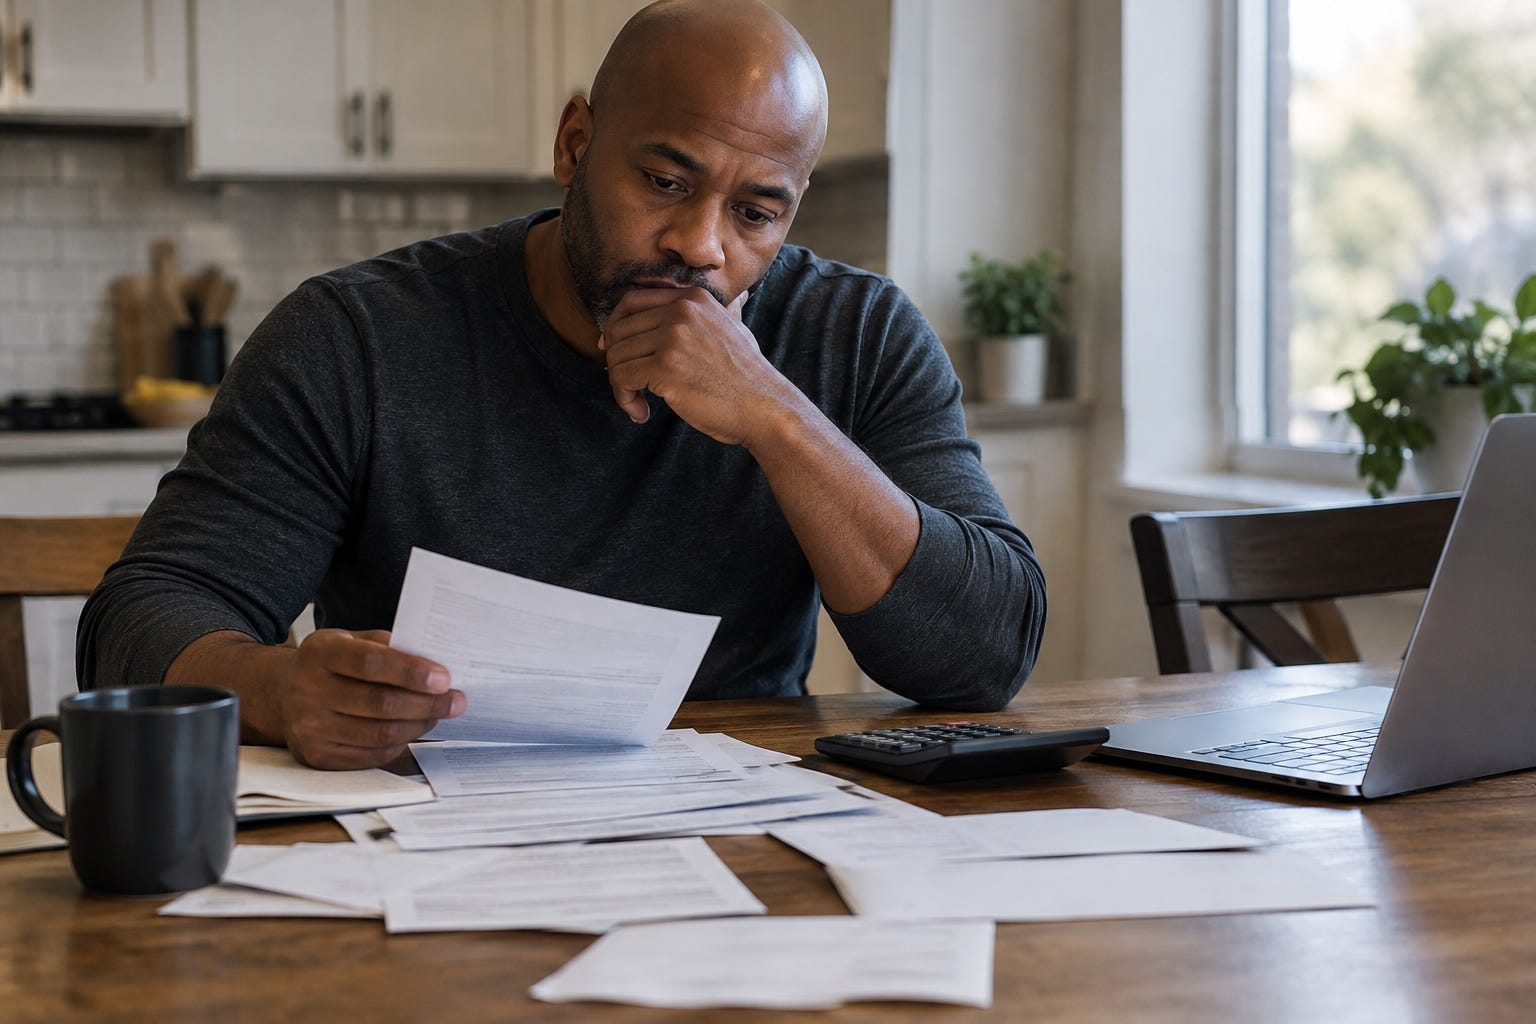
In Monday’s column, “When the bills keep coming,” I shared the uncomfortable reality of my September spending. I spent $8,196.63 on my credit card, my highest monthly total of the year.
That number was difficult to confront, but the spending is only part of the problem. The bills keep coming, and the debt I’ve accumulated needs to be addressed.
Now I have some tough decisions to make.
I need to get lean. Again. And this time, it requires more than skipping restaurants for a month or cutting back on discretionary expenses like marijuana and alcohol.
My circumstances call for drastic measures, none of which are ideal.
I have to figure out where to cut back, what to put on hold and how to free up money to service my debt.
The irony isn’t lost on me. I’ve been working to get smarter with money, investing aggressively and trying to build a future with more freedom and options. Yet here I am, confronting the reality of being invested well but cash poor.
I have money working toward my future while struggling to manage the financial demands of my present.
Something has to give. The question is what.
My tithe is on the table. So are my investments: my IRA, taxable brokerage account, HSA and the money I’ve been dollar-cost averaging into Bitcoin.
I may even have to reconsider contributions to Parker’s investments.
I hate the thought of pausing my investing. I’ve been trying to make up for lost time, and I know how much consistency and compounding matter. Building wealth for my family has become central to how I think about my future and the life I want to help create for Parker.
The idea of interrupting that progress to deal with debt is a tough pill to swallow.
But the disappointment goes deeper than the money.
I genuinely thought I’d graduated to the next level. I thought I’d put enough distance between myself and some of my old financial habits to feel more secure.
Having to reconsider decisions I thought I was past making feels like starting over.
I know the progress I’ve made hasn’t disappeared, but that doesn’t make this realization any easier to accept.
And there’s another expense rearing its head. I haven’t yet had to pay any interest, but I know I need to account for that possibility, too. I’m already trying to get a handle on the debt in front of me, and the thought of another financial obligation adds to my uncertainty.
I don’t have this figured out. I’m still weighing my options, confronting where I stand and wrestling with the sacrifices I have to make to move forward.
I keep reminding myself that this is a season. I may have to slow down some of the things I’ve been working toward to deal with the reality in front of me, but that doesn’t mean I’ve abandoned the destination.
The storm hasn’t passed. I’m still in it, still holding on, still trying to find my footing.
I thought I’d be further along by now, and I have to sit with that disappointment. I don’t know exactly how I’ll get through this or how long it will take. But I still believe brighter days are ahead.
I just know I have work to do, and I’m going to keep doing it.

Meditate

Editor’s note: This is Part 3 of a five-part series, “R-E-M-E-W,” built around five essentials I’ve come to believe are worth making part of everyday life. Each installment explores one of the practices I’m learning to prioritize as I figure out what it means to live well.
To every father carrying more than he lets on

To the father lying awake at night worrying about money, custody, your children or the future — I see you because I’ve been you.
Can't beat yourself up. It happens! Good thing is your investments will still compound. Maybe slow down a bit. I myself went down to around $50 into my brokerage a week when I hit a financial storm. It's still money going to work while you focus on other areas.
I don’t think we ever graduate from money concerns. We just get better at understanding and managing them. What you’ve done is given yourself options. You have time to rebuild. Remember, this is what money is for, to be deployed as needed.