

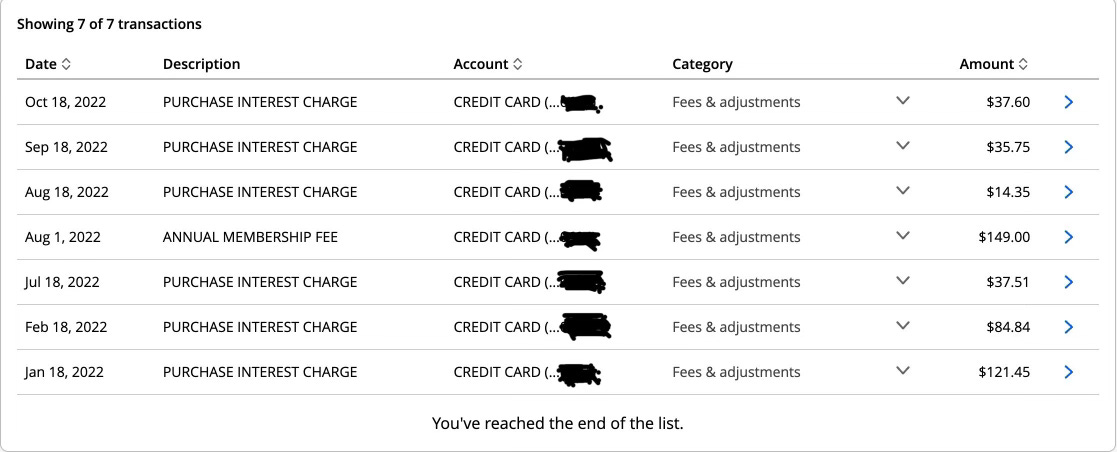
For four years, I didn’t pay a penny in credit card interest.
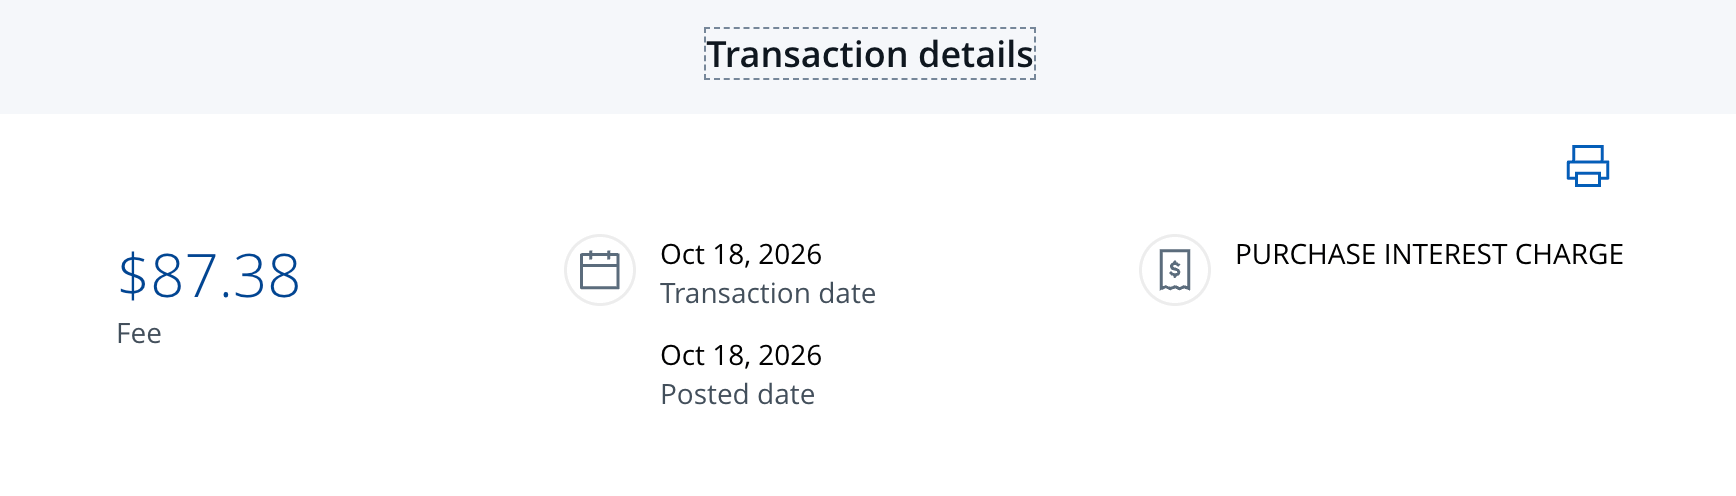
My last interest charge was Oct. 18, 2022. I didn’t pay interest again until Sunday.
Oct. 18, 2026.
Exactly four years to the day, my credit card statement hit me with an $87.38 purchase interest charge.
The total represented more than money leaving my pocket. It was a painful reminder that years of diligence, responsible spending and paying my balance in full every month couldn’t protect me from being knocked off track.
I never expected to be back here, especially not after being so deliberate about my finances. But mounting legal bills have changed my financial reality in ways I couldn’t have anticipated.
And that’s a tough reality to accept.
It’s not that $87.38 will ruin me. It’s what the charge represents: how quickly circumstances can threaten the stability you’ve spent years building.
Life doesn’t always care how responsible you’ve been.
Since 2023, I’ve put the majority of my expenses on a credit card and paid the balance in full every month. That was my system: spend responsibly, collect the rewards, avoid interest and keep moving toward financial freedom.
Then came the legal bills.
I’ve been fighting an ongoing legal battle since the spring, and the expenses have continued to pile up. When the bills keep coming, the money has to come from somewhere.
Now I’m carrying more than $6,500 in credit card debt. My goal is to pay it off by the end of November or, at the latest, the middle of December. Getting there, however, means making choices I never expected to face again.
I’ve paused all my investments, including the money I invest monthly for Parker’s future.
That decision stings the most. Every month I don’t contribute is a month I’m putting her financial head start on hold.
But I can’t keep investing as though nothing has changed while carrying credit card debt at a high interest rate. Something has to give, at least temporarily.
And the credit card interest may not be the end of it. I’m likely to incur interest on attorney fees, too. The financial consequences of this legal battle could follow me well beyond the day it’s resolved.
This legal storm is taking resources away from the person I love most. Money that could be invested in Parker’s future is going to attorneys instead.
That’s the trade-off that hurts most. Parker should be benefiting from the resources I’m working so hard to build — not losing opportunities because the adults responsible for her keep dragging this out instead of finding a better way forward. Some battles may be necessary, but their costs don’t stop with the people fighting them.
I haven’t forgotten how to manage money properly. But knowing how to manage money doesn’t mean I can prevent every financial setback.
I’m not going to pretend this detour doesn’t hurt.
More than anything, this year has taught me that financial progress isn’t always a straight line. You can do the right things for years and still find yourself fighting to protect the ground you’ve gained.
My immediate goal is clear: pay off the debt, stop the interest from accumulating and get back to building the future I’ve worked so hard to create.
Four years without credit card interest didn’t mean I’d figured everything out. I’d simply built a system that worked — until circumstances changed.
Now I have to work my way back.
This is a setback, not a surrender.
But I can’t wait to get off this ride.

How to use credit cards wisely and avoid debt

A young professional recently asked me how to use a credit card, which caught me off guard.
Transform your finances today with this essential tool

The most valuable financial weapon in my arsenal comes from my primary credit card — the spending planner.
Many of us call this a stumbling block - - "We fall down, but we get up!" - - also a lesson that Parker needs to see you handle properly. Yes, You Can!!